Canada
Your credit history did not move to Canada with you
|Subscribe·Archives·Current Issue
Your credit history did not move to Canada with you
Canadian credit bureaus only see Canadian activity. Here are 4 steps to start yours.
Newcomer Digest

Newcomer Digest

Trivia Question❓

How many provinces and territories does Canada have?

Answer at the bottom of the newsletter

Newcomer Digest – Thursday's Edition

By the Newcomer Digest Team · A weekly guide for newcomers to Canada

Credit scores in Canada usually run from 300 to 900, and the credit bureaus only count credit activity in Canada. This week, four steps to start building yours.


In this issue:

  • The story: Why your home-country credit history does not show up here
  • What it means: The habits that move a Canadian score
  • What to do: Four steps, starting with a free report
  • Resource: Free reports from Equifax and TransUnion

Featured Story

Your Credit History Did Not Move to Canada With You

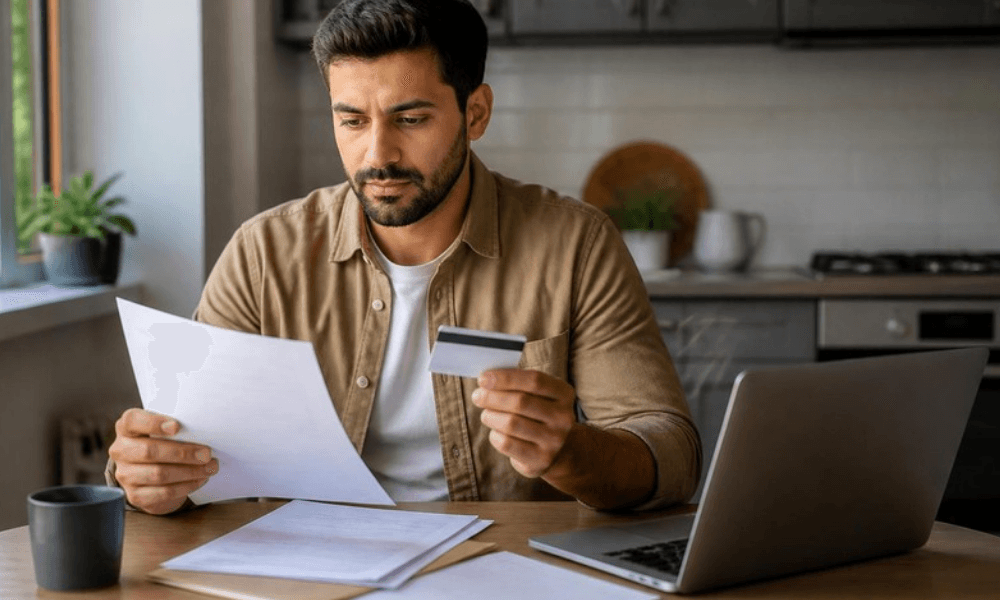
A newcomer reviewing a bank statement and a credit card at a kitchen table


Canadian credit bureaus only collect credit activity in Canada, so building a score starts with what you do here.

You apply for a phone plan. Or an apartment. Or a card. The answer comes back: not enough credit history.

You paid every bill on time back home. That did not travel with you.


Here is the short version, from the Financial Consumer Agency of Canada (FCAC).

  • A credit report is a summary of how you have used credit in the past. The credit bureaus create it when you first borrow or apply for credit.
  • A credit score is a three-digit number based on that report. Scores usually range from 300 to 900. Higher is better.
  • The bureaus only collect Canadian credit activity. Credit from another country does not appear on a Canadian report.

Some lenders may still look at your credit history from another country. You may need to bring a foreign credit report and meet with a bank officer.


Read the full guide on our website

What This Means for You

Your score is built from habits, starting now


FCAC groups the factors that go into a score in two parts.


  • Credit history: how long you have had credit and how long each account has been open.
  • Credit habits: missed payments, how much you owe, how close you are to your limit, and how often you apply for new credit.

FCAC says payment history is the most important part of your credit score.


Where newcomers commonly go wrong:

  • Assuming the score from home transfers. The bureaus do not collect it.
  • Applying for several cards at once. Hard inquiries, like card or mortgage applications, can affect your score.
  • Using almost the whole limit. FCAC's example: owing $4,500 on a $5,000 limit can look riskier to lenders than owing $1,000.
  • Skipping a payment during a dispute. FCAC says do not skip a payment, even if you are disputing a charge.


This is general information, not financial advice. Check with your financial institution and the official pages below for your situation.

Advertisement
Advertisement

What You Can Do Now

Four steps to start your credit history


  1. Get your free reports. Equifax and TransUnion both offer free online access. Checking your own report or score does not affect your credit rating. If you have no Canadian credit activity yet, there may be little to see. That is the starting point.
  2. Open one account you can afford. Ask your bank which card you may be offered. FCAC says a secured card may be an option if you have no credit history, and it names newcomers to Canada. You give a deposit, and your limit is normally equal to or higher than it. Before you pay, ask: is the deposit insured, is it a recognized brand such as Visa or Mastercard, and does the issuer report to Equifax and TransUnion?
  3. Pay on time, every time. Pay in full if you can. If you cannot, pay at least the minimum, and call your lender right away if you expect trouble. Ask about alerts for due dates.
  4. Keep the balance low. FCAC says to try to use less than 30% of your total limit. Example: $1,000 used on a $5,000 limit is 20%.


FCAC: Getting your credit report and credit score
FCAC: Improve your credit score
FCAC: Choosing a credit card, including secured cards

Helpful Resource

Free credit reports


The Financial Consumer Agency of Canada explains how to get your report and score from both bureaus, online, by mail or by phone.

  • Website: Getting your credit report and credit score (FCAC)
  • Equifax Canada: 1-800-465-7166
  • TransUnion Canada: 1-800-663-9980
  • Free score: Equifax in all provinces and territories. TransUnion only in Quebec and Ontario, with your Consumer Disclosure.


Know a newcomer who was told "no credit history"? Forward this edition to them.

What money question should we answer next? Reply to this email and tell us.

From the publisher

Today's newsletter is brought to you by:


How does your child learn best?


Answer 7 quick questions and get a free, personalized study-style report by email. No login needed.


Then talk to certified teachers about a plan that fits: online tutoring, or in-home tutoring in Edmonton.


8-year Consumer Choice Award winner, Northern Alberta


💡 Answer to Trivia Question:
13: 10 provinces and 3 territories (the Northwest Territories, Yukon and Nunavut).

Before you go


Every newcomer has questions that nobody answers clearly. We answer them one at a time, in plain language, with sources you can check.


Your turn. Reply to this email with the one question you'd like us to cover next. Your replies shape what we write.


Know someone new to Canada? Forward this email to them. It's the best way to help.


Missed an issue? Read them all at newcomerdigest.com/archives.

Newcomer Digest

© 2026 Newcomer Digest.

Newcomer Digest is the twice-weekly briefing for people building a stable life in Canada. Every Monday and Thursday, we turn immigration changes, PR pathways, job-market shifts and Canadian workplace culture into clear next steps you can use that week. No jargon. No panic. No fake positivity. Just practical, honest guidance to help you protect your career, understand your options, and move forward with confidence.

© 2026 Newcomer Digest.